All Categories
Featured
Evaluating Term vs Whole Life Insurance
That versatility can be big if your earnings changes from year to year, or you go through a big life occasion (such as divorce or short-term work leave) and still desire to keep your policy in force. However it likewise means you'll need to pay closer attention to your policy in time.
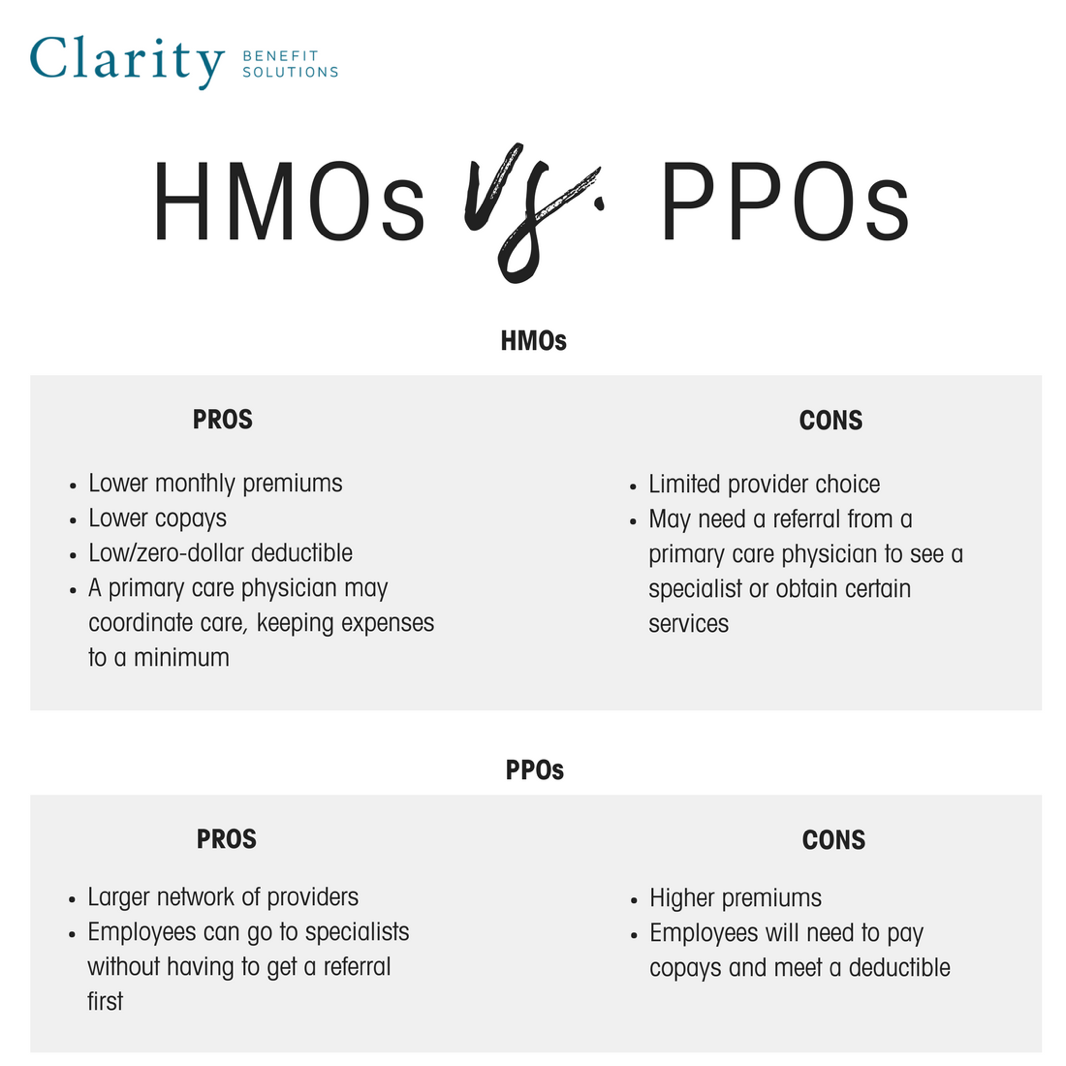
This table highlights the biggest distinctions: Both whole life insurance and indexed universal life offer you with irreversible protection that builds money worth, however how that money value grows is rather different. Entire life insurance usually has ensured growth at a set rate, while IUL has the potential for higher returns due to the fact that its money value is tied to a market index.
Medicare in IrvineTerm life insurance coverage is usually the most affordable and most convenient type of life insurance to get. It doesn't build cash worth, however you get a guaranteed survivor benefit for a set amount of time, typically at a fraction of the expense of an IUL policy. You can believe of a variable universal life insurance coverage policy as one step above an IUL policy in regards to threat and benefit.
Medicare in Irvine
This implies you'll have greater development potential however likewise the possibility of financial investment losses. Like any financial product, indexed universal life insurance has advantages and compromises. If your primary objective is merely changing your earnings for your household, a term life insurance policy is generally easier and far less costly.
Comparing Term vs Whole Life Policies
Common costs might consist of:, which typically increases as you age for handling the policy subtracted from your payments if you include functions like long-lasting care or chronic disease benefits if you cancel the policy throughout its early years Before you buy an indexed universal life policy, the insurance coverage company will normally provide an illustration revealing how your policy might perform in time.

Latest Posts
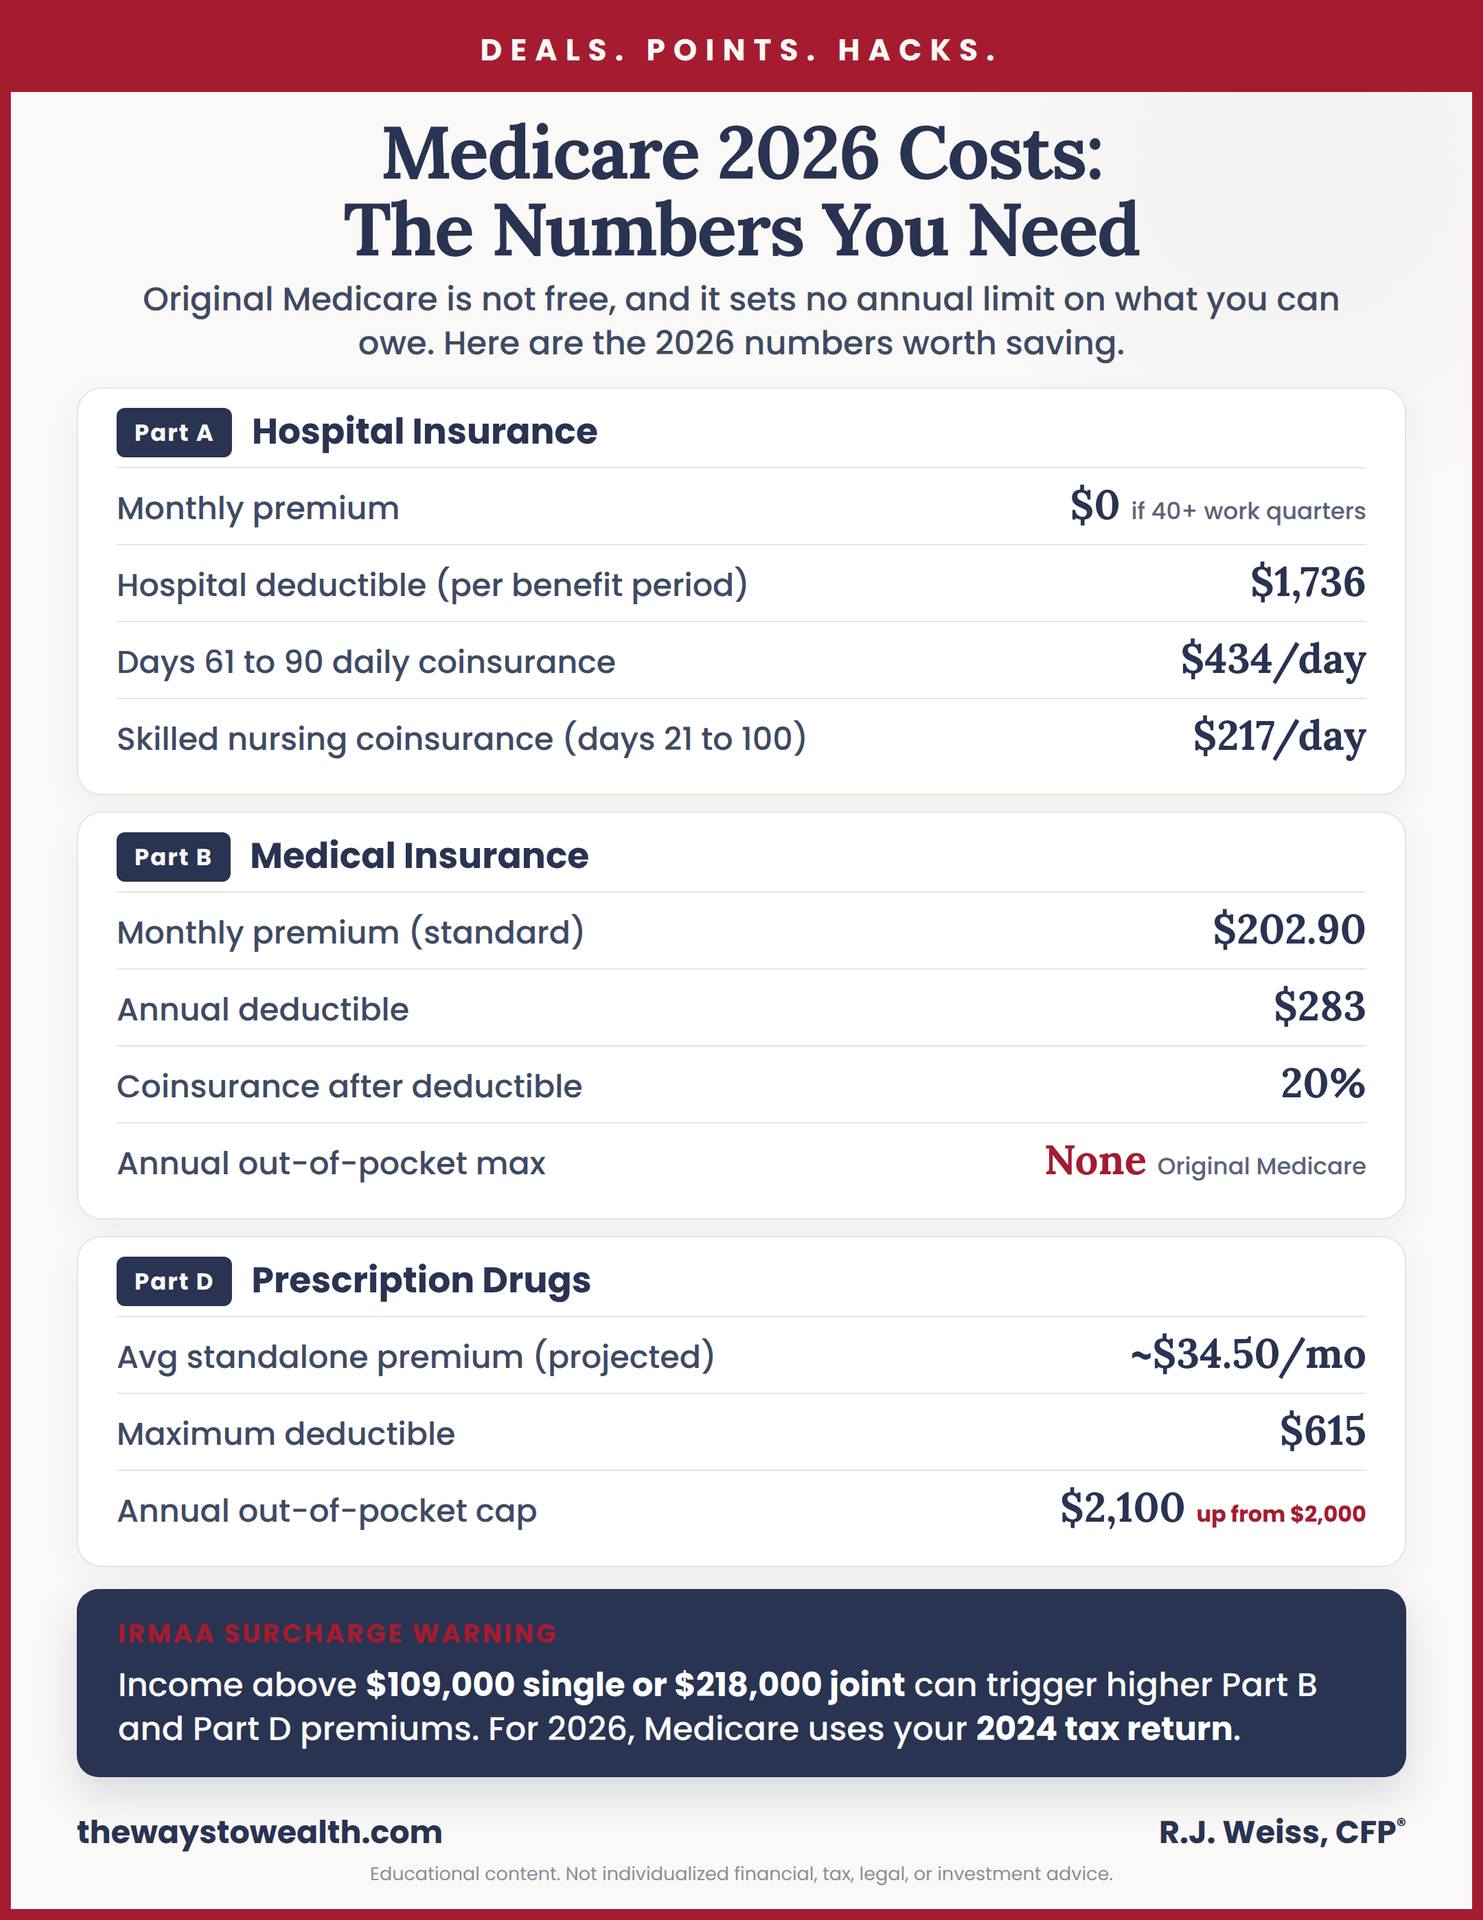
Selecting the Best 2026 Medicare Supplement Plans
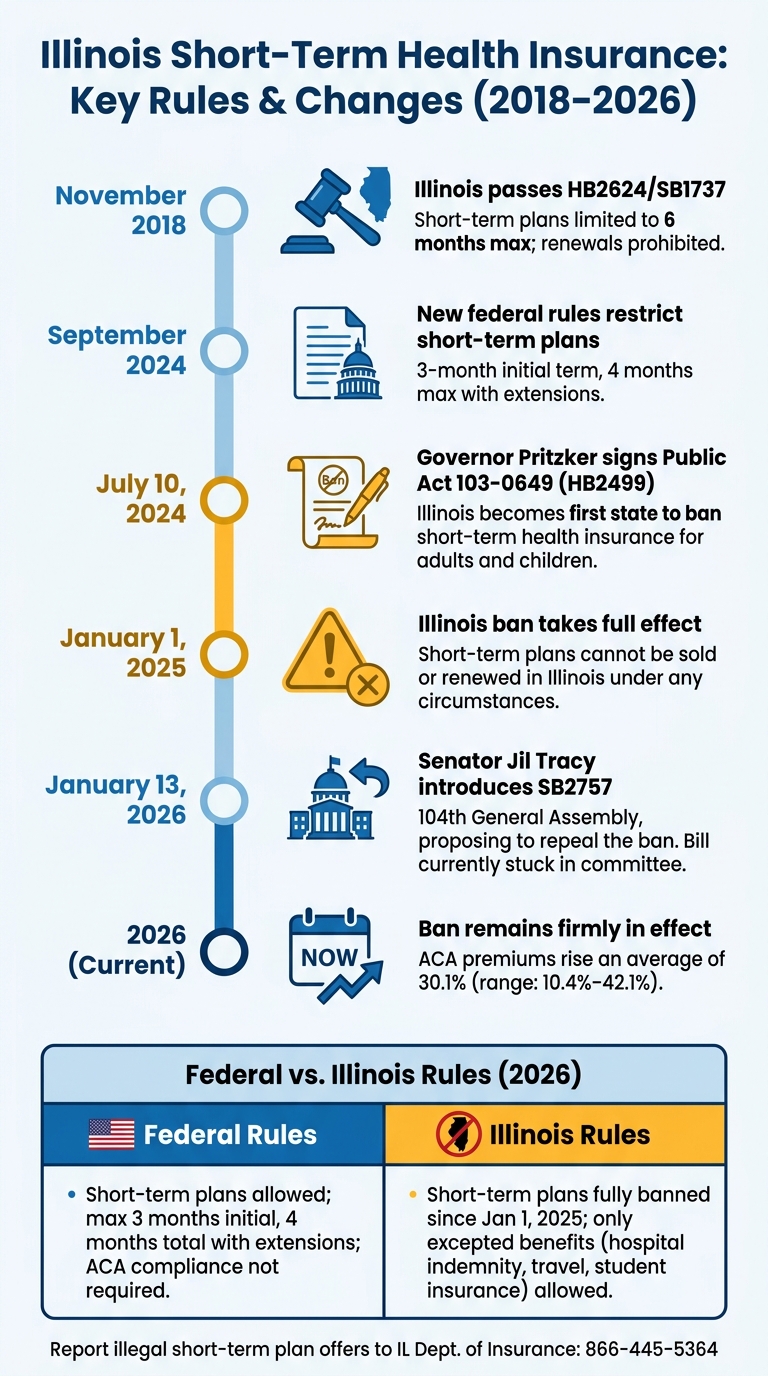
Building Long-Term Financial Security Through Life Insurance
Evaluating Term vs Whole Life Insurance